Most first-time buyers plan for one number: the EMI. The dealer quotes it, the bank approves it, and it feels like the cost of the car. But the EMI is only the largest line in a monthly budget that also includes fuel, insurance and servicing, and the road tax you paid on day one is quietly sitting inside that loan.
This guide puts all of it on one page. We will take two popular first cars, the Maruti Swift and the Brezza, work out their on-road price, and turn that into a realistic monthly figure you can test against your salary.
Quick Answer:
The true cost of owning a car in India goes beyond the monthly EMI. Fuel, insurance and servicing also add to the expense. Based on the examples, the Maruti Swift costs around ₹19,300 per month, while the Brezza costs around ₹22,200, before servicing. Planning for these expenses helps first-time buyers choose a car that fits their budget.
Key Takeaways
- Compare on-road prices, as road tax, insurance and registration increase the car’s actual cost.
- Budget for fuel, insurance renewals and servicing in addition to your monthly EMI.
- Choose an affordable loan tenure and down payment to reduce the overall interest burden.
Step 1: Start with the on-road price, not the ex-showroom price
The price in advertisements is the ex-showroom price. Nobody actually drives away for it. The on-road price adds road tax set by your state, insurance, registration and FASTag, and a few fixed charges. If the car’s ex-showroom price is above ₹10 lakh, 1% TCS is also collected, though you can claim it back against your income tax.
Here is the Delhi breakdown for two common first cars, using on-road figures from CarMaths (prices checked October 2026):
| Line item | Maruti Swift VXi 1.2 Petrol MT | Maruti Brezza LXi 1.0 Turbo MT |
| Ex-showroom price | ₹6,67,900 | ₹7,49,900 |
| Road tax + cess | ₹51,955 | ₹57,843 |
| Insurance (first year, estimate) | ₹33,395 | ₹37,495 |
| Registration and FASTag | ₹1,200 | ₹1,200 |
| Hypothecation and handling | ₹1,900 | ₹1,900 |
| On-road price, Delhi | ₹7,56,350 | ₹8,48,338 |
Two things stand out. First, road tax and insurance together add about ₹85,000 to ₹95,000 to the sticker price. Second, road tax depends on where you register the car. The same Swift costs ₹66,382 more on the road in Karnataka than in Delhi on the base LXi variant, so always check the price for your own state.
Watch the tax bands
Delhi taxes a petrol car at 4% of its ex-showroom price up to ₹6 lakh, 7% from ₹6 lakh to ₹10 lakh, and 10% above that, and the higher rate applies to the whole price. Delhi also adds a flat ₹2,000 below ₹6 lakh and ₹4,000 above it, plus a charge of 0.18% of the price, which is how 7% of the Swift VXi’s price (₹46,753) becomes ₹51,955 of road tax and cess. On the Swift, moving from the LXi to the VXi adds ₹84,000 ex-showroom but ₹1,13,748 on the road, because the VXi crosses the ₹6 lakh line. A small upgrade to the next variant can cost more than it looks.
Step 2: Work out the EMI
A car loan is written against the on-road price, so road tax and insurance are usually financed along with the car. For our example we use the default settings of the CarMaths EMI calculator: a 20% down payment, an interest rate of 8.75% a year, and a five-year tenure. Your bank’s rate will depend on your credit profile, and processing fees are extra.
The standard EMI formula is:
EMI = P × r × (1 + r)^n ÷ ((1 + r)^n − 1)
where P is the loan amount, r is the monthly interest rate (8.75% ÷ 12) and n is the number of months.
Worked example: Maruti Swift VXi
- On-road price: ₹7,56,350
- Down payment (20%): ₹1,51,270
- Loan amount: ₹6,05,080
- EMI over 60 months at 8.75%: ₹12,487
- Total interest over five years: ₹1,44,151
For the Brezza LXi Turbo, the down payment is ₹1,69,668, the loan is ₹6,78,670 and the five-year EMI comes to ₹14,006, with ₹1,61,682 of interest.
Longer tenure: lower EMI, higher total cost
Stretching the loan is the easiest way to make a car feel affordable, and the costliest. On the Swift, a seven-year loan cuts the EMI to ₹9,659, which is ₹2,828 less each month than the five-year loan, but you pay ₹2,06,241 in interest, which is ₹62,090 more. A three-year loan raises the EMI to ₹19,171 but keeps total interest down to ₹85,078.
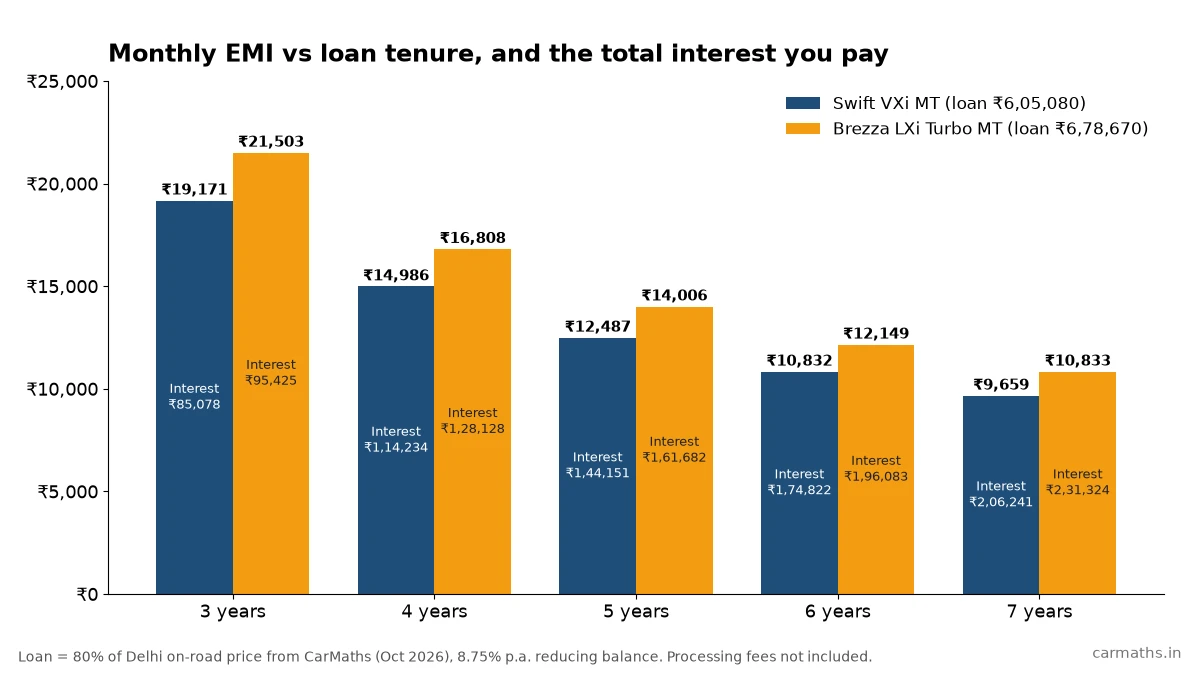
If the five-year EMI already feels tight, a longer tenure usually means the car is too expensive for your budget right now. It is better to look at a lower variant, a bigger down payment or a cheaper car.
Step 3: Estimate fuel
Fuel is the cost that grows with how much you drive, so use your own numbers. Our assumptions:
- You drive 1,000 km a month (12,000 km a year).
- Petrol costs ₹102.12 a litre, the Delhi pump price CarMaths read on 25 September 2026. Use your city’s current price.
- Mileage is the manufacturer’s certified figure shown on CarMaths: 35 kmpl for the Swift petrol manual and 19.96 kmpl for the Brezza 1.0 Turbo.
That works out to about 39.4 litres, or ₹4,028 a month, for the Swift, and about 50.1 litres, or ₹5,116 a month, for the Brezza.
Certified mileage comes from a fixed test cycle, not city traffic. If you get 20% less in daily use, the monthly fuel bill rises to about ₹5,036 for the Swift and ₹6,395 for the Brezza. It is wise to plan with this higher figure.
Step 4: Set aside money for insurance and servicing
Insurance:
Your first year of insurance is paid upfront as part of the on-road price, and third-party cover for three years is included. But own-damage cover has to be renewed every year from the second year. To be safe, we set aside one-twelfth of the first-year premium every month: ₹2,783 for the Swift and ₹3,125 for the Brezza. Renewals often cost less as the car’s insured value falls, so treat this as a ceiling, not a quote. Keeping the money aside every month means the renewal never surprises you.
Servicing:
Both cars come with a manufacturer warranty of 3 years or 1,00,000 km, whichever is earlier, but routine services, tyres, wipers and batteries still cost money. Service costs depend on your dealer and how far you drive, and CarMaths does not publish them, so we leave them out of the totals below. Ask your dealer for the service schedule and the price of each visit, divide the yearly total by 12, and add it to your monthly figure.
Step 5: Put it all together
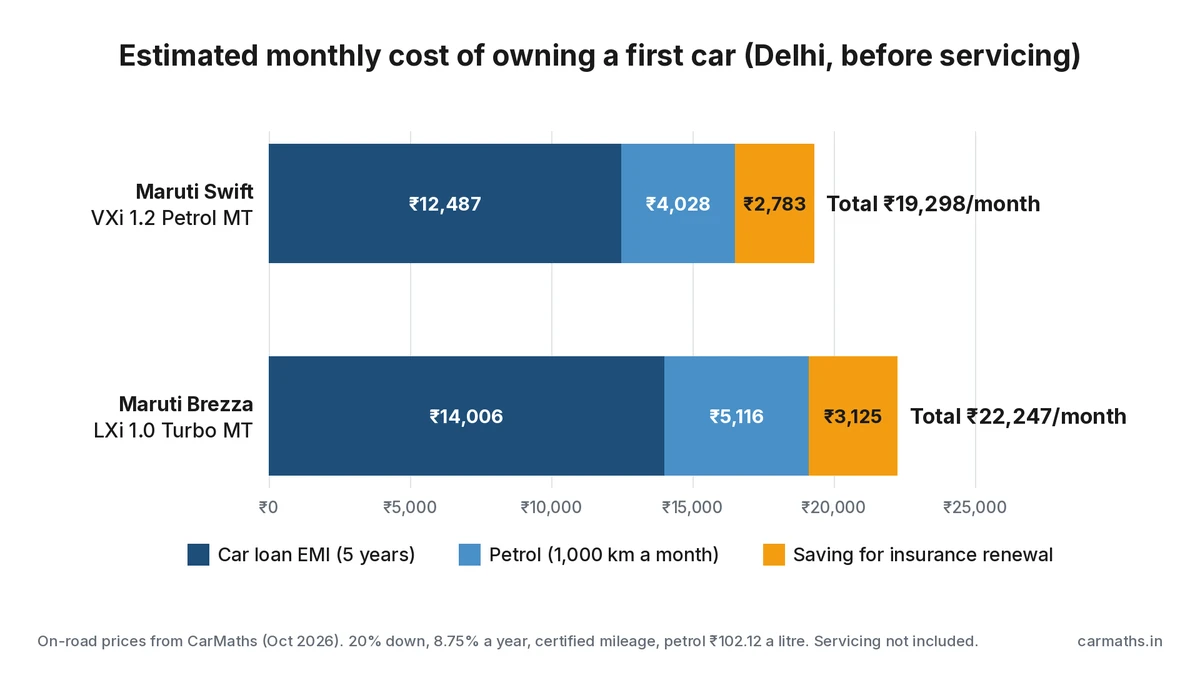
| Monthly cost (Delhi) | Swift VXi MT | Brezza LXi Turbo MT |
| EMI (5 years, 8.75%, 20% down) | ₹12,487 | ₹14,006 |
| Petrol (1,000 km, certified mileage) | ₹4,028 | ₹5,116 |
| Saving for insurance renewal | ₹2,783 | ₹3,125 |
| Servicing (ask your dealer) | Not included | Not included |
| Total per month, before servicing | ₹19,298 | ₹22,247 |
So before servicing, the true monthly cost of the Swift is about ₹19,300, or about 1.5 times its EMI, and the Brezza’s is about ₹22,200. Plan with real-world mileage, 20% below the certified figure, and those become about ₹20,300 and ₹23,500. This still leaves out servicing, parking, tolls, cleaning or the occasional fine, so keep a small buffer on top.
After the loan ends, the monthly cost falls to running costs alone: about ₹6,811 for the Swift and ₹8,241 for the Brezza on these assumptions, plus servicing.
Road tax: the one-time cost hidden in your EMI
Road tax does not show up as a monthly bill, which is why many buyers forget it. Yet it is one of the largest single charges: ₹51,955 on the Swift VXi and ₹57,843 on the Brezza LXi Turbo in Delhi. The loan is 80% of the on-road price, so 80% of the road tax and insurance is borrowed too, about ₹68,300 on the Swift, and it carries interest for the full tenure. A bigger down payment is what brings that down: each extra ₹50,000 you put down saves about ₹11,900 of interest on the Swift over five years.
A simple checklist before you sign
- Compare on-road prices, not ex-showroom prices, for your own state and the exact variant you want.
- Check the tax bands. A variant just above a band can cost much more on the road.
- Fix your tenure first. If the five-year EMI does not fit, choose a cheaper car rather than a longer loan.
- Add fuel, insurance and servicing to the EMI before you decide what you can afford.
- Question the negotiable lines. Own-damage insurance can be bought from any insurer, and dealer handling charges are not government fees.
- Keep an emergency fund separate. Your down payment should not empty your savings.
The bottom line
A car that “costs ₹12,487 a month” actually costs about ₹20,300 once you add insurance and fuel at real-world mileage, and servicing comes on top. That is not a reason to avoid buying a car. It is a reason to budget for the real figure. Pull up the on-road price for your state, run your own numbers through an EMI calculator, add the running costs, and you will know exactly what your first car will cost you every month before you sign the papers. For the latest price of every variant, check the official Maruti Swift page before you book.
Lakshmi Sundari is a finance content writer and editor with over four years of experience across financial content and content strategy. She holds an MBA in Finance and writes on investing, personal finance and fixed-income markets. Her work spans long-form articles, PR, thought leadership, newsletters and social media, along with editorial planning and content strategy. She focuses on explaining financial developments and investment concepts through research-backed, practical writing.