Deciding whether to buy a house with a home loan or rent is one of the most crucial financial decisions for an Indian family. Purchasing a house will give you ownership and stability along with the opportunity to gain profit from its appreciation in value.
Renting, in turn, offers more flexibility and requires less initial investment, allowing you to use your money more effectively. Thus, when choosing between renting and buying in 2026, you need to take into account factors such as property costs, rental rates, home loan interest rates, financial stability, tax breaks, and how long you plan to stay in one place.
Your decision should not be based merely on the expenses. It should help you achieve your financial goals without being too demanding of your finances.
This guide will help you decide between a home loan and rent in India in 2026 and compare the expenses of purchasing and renting a property.
Quick Answer:
Choosing between a home loan and renting in India in 2026 depends on your budget, income stability, property prices, interest rates, and future plans. Buying a home can help build ownership over time, while renting offers greater flexibility and requires less upfront money. Compare EMIs, interest, maintenance, taxes, rent increases, and other costs before deciding which option suits your financial goals.
Key Takeaways
- The cost of a home loan vs rent in India in 2026 would depend on property costs, interest rates, rent, income stability, and other factors. Owning the property is one option that may offer appreciation and security, but renting would be an option with flexible choices and a low initial cost.
- Assess the Total Cost Before Making any Choice. The costs of a home loan would include the down payment, EMI, stamp duty, registration, maintenance costs, and other expenses. Rent costs would comprise monthly rent, the deposit, and rent increases.
- Choose One of the Options as per your Financial Position. A home loan is one option for those who wish to stay in one place permanently with stable earnings and savings. But rent would be one of the best options for those who need some flexibility and wish to move in the future.
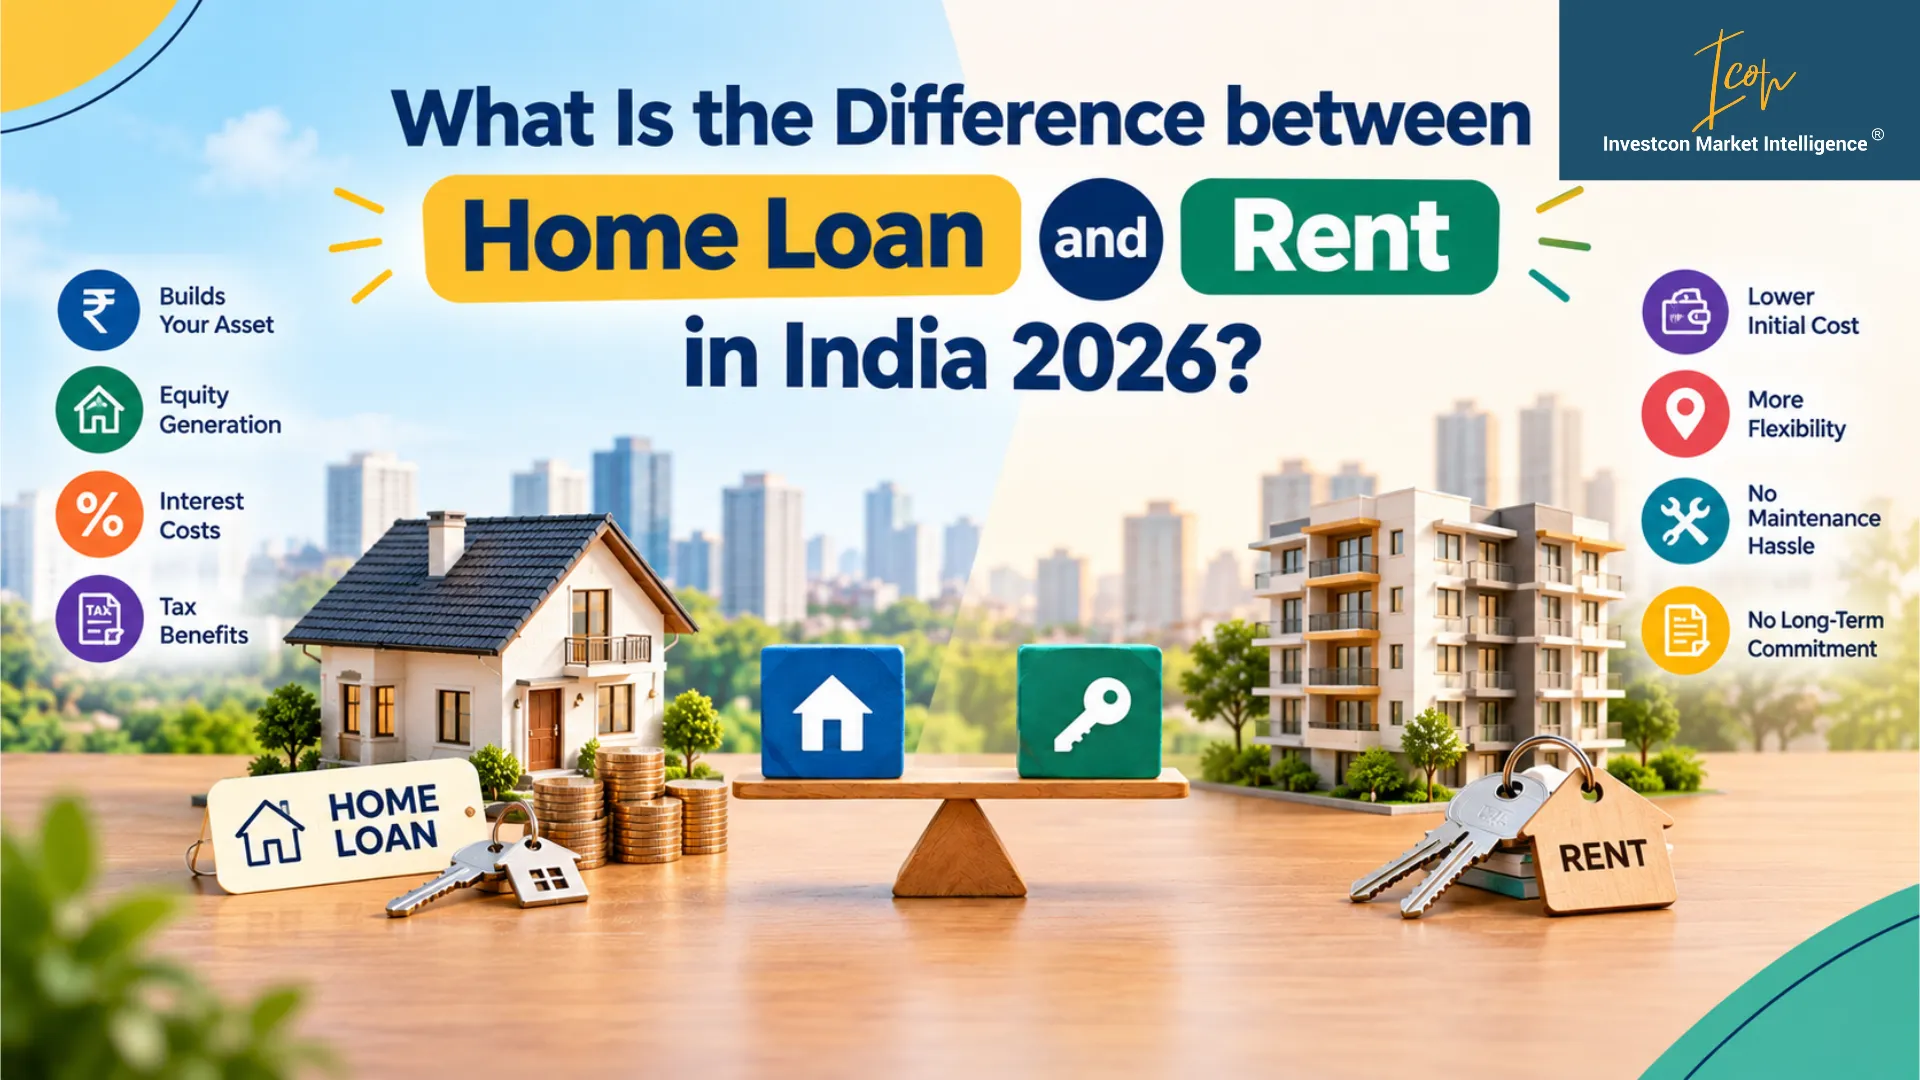
What Is the Difference between Home Loan and Rent in India 2026?
When buying a property with a home loan, the buyer borrows part of the purchase price from a bank or housing finance company and repays it through EMIs. The property generally serves as security for the loan. As the principal is repaid, the borrower’s equity in the property increases, and the lender releases its charge and property documents after the loan is closed.
When renting, the tenant pays the landlord for the right to occupy the property without acquiring ownership. Upfront costs may include a security deposit, brokerage and moving expenses, followed by monthly rent and any maintenance charges specified in the rental agreement.
| Factor | Buying with a home loan | Renting a property |
| Initial cost | Down payment, registration, stamp duty, and other charges | Security deposit, brokerage, and moving costs |
| Monthly payment | EMI, maintenance, and other ownership costs | Rent and applicable maintenance charges |
| Ownership | Build ownership as the loan principal is repaid | No ownership is created |
| Flexibility | Selling or relocating can be expensive | Usually easier to relocate, subject to the lease |
| Repair and maintenance | Owner bears many major expenses | Responsibilities depend on the rental agreement |
Costs Associated with the Process of Purchasing a House in India by 2026
Apart from the purchase cost of a house, there are other costs that must be considered during the purchase process.
Down Payment and Upfront Costs: It is common practice for home loans to account for a portion of a property’s eligible cost. The buyer will have to cover the remaining cost of the property, along with other costs not covered by the home loan.
Down payment: This is the amount of money paid from your personal finances. The down payment is usually determined by the property’s cost and other home loan requirements.
Stamp duty and registration: The cost varies by state and the transaction, but it can cover some of the upfront costs of buying a house.
Processing costs: These include loan processing, legal verification, and valuation.
Furnishing costs: For new homes, the buyer will have to incur expenses for furniture and fittings.
The observation is that there is an increase in the cost of borrowing in the housing loan market of India during the period 2022 to 2023. There is an increase in the Repo Rate from 4.00% to 6.50%. This increase has taken place because of the increase in the monetary policy rate due to inflation, as set by the Reserve Bank of India.
According to the data provided by RBI, there has been an increase in the weighted average lending rate of new housing loans benchmarked externally from April 2022 to August 2023 by 127 basis points. The reason behind this is an increase in the benchmark rates resulting in higher lending rates.
Monthly EMI and Interest Cost
EMI comprises principal and interest components. In a normal long-tenure loan, a higher proportion of each EMI comprises the interest component, although, depending on the terms and repayment pattern, the actual breakup differs.
Your home loan interest ROI or rate of interest will impact the overall cost of repayment. Even a small difference in ROI will make a substantial difference to your cost of borrowing given the size of the loan and tenure.
Office and Residential Market H2 2025 observed that there was an increase in prices of residential properties of 19% year-on-year in the NCR region in 2025.
Bengaluru saw an increase of 12% while Hyderabad had an increase of 13%. The reason behind the increase in prices was the strong demand for high-end and high-rise homes, alongside modifications in launch and financial schemes.
As an example, if a property is valued at ₹80 lakhs and there is an increase of 19%, then the value will be ₹95.2 lakhs.
Ongoing Costs of Ownership: Apart from the EMI, there are some costs involved with owning a house, which could make a purchase more or less viable.
Maintenance and repairs: The costs of plumbing, electrical, painting, and other maintenance and repairs could become a burden. Apartment residents have to bear monthly maintenance costs paid to the society.
Cost of property tax and insurance: Property tax imposed by the municipality and property insurance are additional yearly costs of property ownership.
Costs of renovation and replacement: Some appliances, fixtures, and other parts of the building structure must be replaced repeatedly.
Opportunity cost: The amount invested as a down payment and transaction costs can’t be used elsewhere.
Indian Home Loan Interest Rates 2026 and Their Effect
Interest rates play an important role in decisions about taking out a home loan or renting a house. These interest rates vary depending on the bank, the borrower’s credit score, income, loan size, property, and other loan terms.
On 7 October 2026, the Reserve Bank of India increased its repo rate by 0.25 percentage points to 5.50%. Borrowers with floating-rate loans tied to external benchmark rates may be affected, but the timing will vary depending on their loan agreements.
There are some factors to keep in mind before opting for a mortgage.
Effective interest rate: This should be calculated based on offers from various banks and housing finance companies, rather than choosing a bank solely because of the starting rate. All processing and other charges need to be taken into account.
Fixed and floating rates: The fixed rate is more certain than the floating rate, which can change based on the index and the spread charged by the lender. Check whether the offered rate is fixed until the end of the tenure.
Total repayment amount: EMI may be lower due to a higher tenure. Compare interest and total repayable amount with other loan amounts and tenures.
Prepayment options: RBI rules prohibit prepayment charges on floating-rate loans to individuals for non-business purposes. For fixed-rate or other loan structures, check the lender’s applicable prepayment terms. Making partial prepayments can reduce the outstanding principal and future interest cost.
Which is Better for Various Buyers – Home Loan or Renting?
It may depend on your financial condition, career prospects, and familial obligations whether you should go for either of the two. Here are some cases where one option may suit you better than the other.
When Home Loan is the Better Choice
You can choose to buy the home if you have a stable financial position and intend to reside in one place for a long.
- Long-term housing plans: Buying may suit you if you expect to remain in the same location for several years, giving you more time to spread transaction costs over the holding period.
- Adequate upfront savings: You should be able to fund the down payment, registration and other purchase costs without exhausting your essential savings.
- Comfortable EMI affordability: Your income should be sufficient to manage EMIs and regular ownership expenses while continuing to meet other financial goals.
When Renting is the better choice
It might make more sense if purchasing a house would compromise your ability to use your money for anything else or require a large loan relative to your income.
- You may relocate soon: Renting can be more practical when your career or personal plans may require you to move.
- You want to preserve liquidity: Renting generally requires less upfront capital, leaving more funds available for savings or investments.
- Property prices are high relative to rents: Where comparable homes can be rented for substantially less than the cost of owning them, renting may be financially more efficient.
- Your income is less predictable: Renting can avoid taking on a large long-term debt commitment.
Best Home Loan in India for NRI Property Buyers
A non-resident Indian (NRI) seeking to buy a house in India can consider home loans from eligible banks and housing finance companies. The best home loan in India for NRI property buyers depends on several factors.
An NRI looking to buy residential property in India can compare home loans based on eligibility, income, country of residence, loan amount, interest rate, tenure and repayment terms. RBI/FEMA rules generally permit NRIs and OCIs to purchase residential and commercial property in India, while restrictions apply to agricultural land, plantation property and farmhouses. Payments must be made through permitted banking channels
Here are some key considerations before choosing a home loan.
- Eligibility and documentation: Requirements differ by lender and may include passport and visa details, overseas employment and income documents, bank statements and property documents.
- Loan terms: Compare the effective interest rate, eligible loan amount, tenure and applicable fees across lenders.
- Currency risk: If you earn in a foreign currency but repay the loan in INR, exchange-rate movements can change the foreign-currency cost of meeting the EMI.
- Property management: If you do not plan to occupy the property immediately, consider maintenance, security, tenant management and periods when the property may remain vacant.
Common Mistakes People Make When Making Comparisons of Home Loan vs Rent
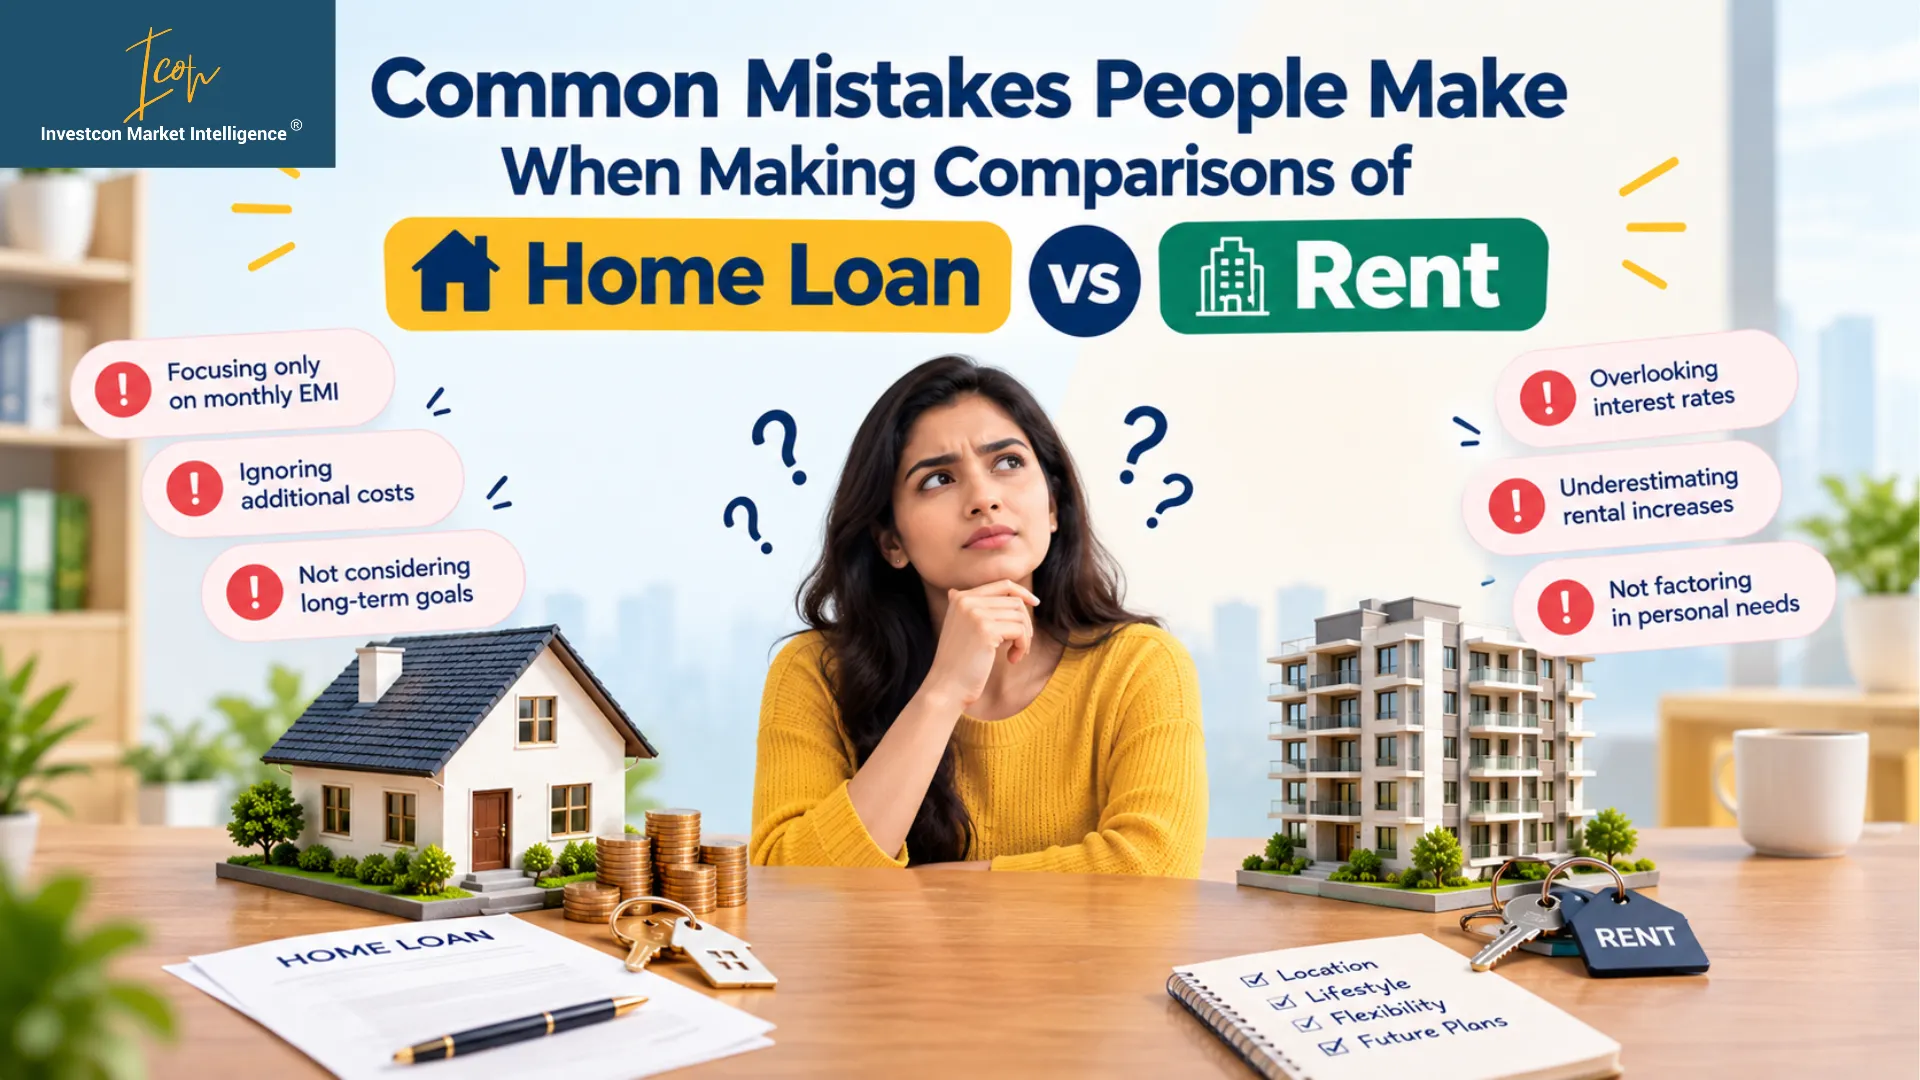
Even after an elaborate calculation, your choice between a home loan vs renting will ultimately prove poor if certain expenses and personal circumstances are not taken into account.
- Comparing only rent with EMI: Compare the overall financial impact of renting and buying rather than treating monthly rent and EMI as equivalent costs.
- Assuming property prices will always rise: Property performance varies by location, supply, infrastructure and demand. The 19% NCR-wide increase reported for 2025, for example, does not mean every property in NCR appreciated by 19%.
- Ignoring investment discipline: Renting may leave more capital available, but its financial advantage depends partly on what you do with those savings.
Bottom Line:
Deciding whether to take a home loan or rent in India in 2026 depends on factors such as affordability, housing costs, expected rent increases, investments, and future plans. The former can help you feel secure and even see some appreciation in your property, while the latter can help you invest the money elsewhere.
You can consider a home loan if you earn steadily, have enough for the down payment, can afford the EMIs, and plan to stay in the house for quite a long time. Otherwise, it will be wise to rent.
FAQs
Q: Should one buy or rent a house in India in 2026?
Ans: It is better to buy a house provided that there is a steady income and sufficient financial resources for a down payment. If it is necessary to move elsewhere or invest money in other businesses, it makes sense to rent a house. The first thing to do is make price comparisons.
Q: Does it make sense to get a mortgage in India?
Ans: A home loan can make sense when you can afford the down payment, EMIs and other ownership costs without putting excessive pressure on your finances. Compare the interest rate, tenure and total repayment cost before borrowing.
Q: Which home loan is the best for NRIs in India?
Ans: The following factors determine the best home loan for NRIs in India: eligibility criteria, interest rate, mortgage term, processing fees, and repayment terms.
Lakshmi Sundari is a finance content writer and editor with over four years of experience across financial content and content strategy. She holds an MBA in Finance and writes on investing, personal finance and fixed-income markets. Her work spans long-form articles, PR, thought leadership, newsletters and social media, along with editorial planning and content strategy. She focuses on explaining financial developments and investment concepts through research-backed, practical writing.